
Bernstein: Clarity Act failure lets stablecoin rewards continue, swift SEC and CFTC rulemaking expected
Regulatory Authority Shifts to Federal Agencies
Senate lawmakers failed to advance the Clarity Act, and Bernstein now expects the SEC and CFTC to move quickly to fill the resulting regulatory vacuum in crypto markets.
What the Clarity Act’s Failure Actually Changes
The Clarity Act was positioned as a legislative framework that would have drawn clearer jurisdictional lines between the SEC and CFTC over digital assets. Its collapse in the Senate does not create a regulatory void so much as it preserves the status quo – and in some corners of the market, that status quo is surprisingly favorable to certain crypto products already in circulation.
One area where the bill’s failure carries direct market implications is stablecoin rewards. Without the Clarity Act establishing new rules around yield-bearing digital assets, platforms can continue offering rewards on idle stablecoin balances. That arrangement, which has become increasingly common among retail-focused crypto services, now faces no imminent legislative threat. Bernstein’s analysis points to this continuity as a concrete near-term consequence of the Senate’s inaction.
The distinction matters because stablecoin rewards occupy a legally ambiguous space. Depending on how regulators classify the underlying relationship – whether the yield constitutes interest, a securities product, or something else entirely – the product’s legal standing could shift dramatically. Congress declining to define that space means the SEC and CFTC inherit the question without a statutory answer to work from.
Bernstein’s view is that both agencies will move swiftly. That expectation reflects the current posture of financial regulators under the existing administration, which has shown appetite for issuing agency-level guidance rather than waiting for congressional action. The practical effect is that crypto firms may face binding rules written by unelected agency staff rather than debated and passed by elected legislators – a procedural outcome with significant implications for how those rules can later be challenged in court.
SEC and CFTC Race to Define the Market
The SEC and CFTC have long competed over jurisdiction in digital assets, and the Clarity Act was partly designed to resolve that competition by statute. Without it, both agencies retain overlapping claims over different categories of crypto assets, and the rulemaking Bernstein anticipates will likely sharpen – or deepen – that jurisdictional tension rather than resolve it cleanly.
The SEC’s traditional authority over securities means it has the stronger claim over tokens that function like investment contracts, while the CFTC’s mandate over commodity derivatives gives it standing over Bitcoin futures and related instruments. Stablecoins, which function more like payment tools than speculative assets, have never fit neatly into either framework. Agency rulemaking in the absence of legislation means each body could attempt to assert authority over stablecoins through interpretive guidance, enforcement actions, or formal rulemaking – each carrying different legal weights and timelines.
Enforcement-driven regulation has historically been the SEC’s preferred approach in crypto, using high-profile cases to establish precedent rather than issuing rules through the formal notice-and-comment process. That approach has drawn consistent criticism from the industry because it creates uncertainty and penalizes firms after the fact rather than giving them advance guidance. If Bernstein’s expectation of swift rulemaking proves accurate, it would mark a shift toward a more formal regulatory posture – one with clearer rules but also rules that arrive without the compromise and deliberation that legislative processes force.
The CFTC, for its part, has generally been viewed as the more crypto-friendly regulator, a perception built on years of statements from CFTC chairs welcoming blockchain innovation while distinguishing speculative crypto derivatives from the underlying asset class. Whether that disposition survives a period of aggressive interagency rulemaking remains an open question. Turf battles between the two agencies have derailed crypto regulatory progress before, and nothing about the Clarity Act’s failure resolves the structural incentive each agency has to expand its mandate.
For stablecoin issuers and the platforms that distribute them, the continuation of idle-balance rewards in the short term is useful commercially but precarious legally. A single enforcement action from either regulator characterizing those rewards as unregistered securities income could trigger immediate compliance crises across multiple platforms simultaneously. The industry has operated in that uncertainty for years, but the expectation of imminent agency rulemaking raises the stakes – what was once a gray area firms could navigate quietly could become an explicit target.
Markets Reading the Regulatory Signal
Crypto markets have become increasingly attuned to regulatory signals, and the Senate’s failure to pass the Clarity Act arrived without the kind of dramatic market reaction that legislative setbacks sometimes produce. That muted response may reflect the degree to which participants had already priced in congressional dysfunction on crypto legislation, where multiple frameworks have stalled over the past several years without delivering binding rules.
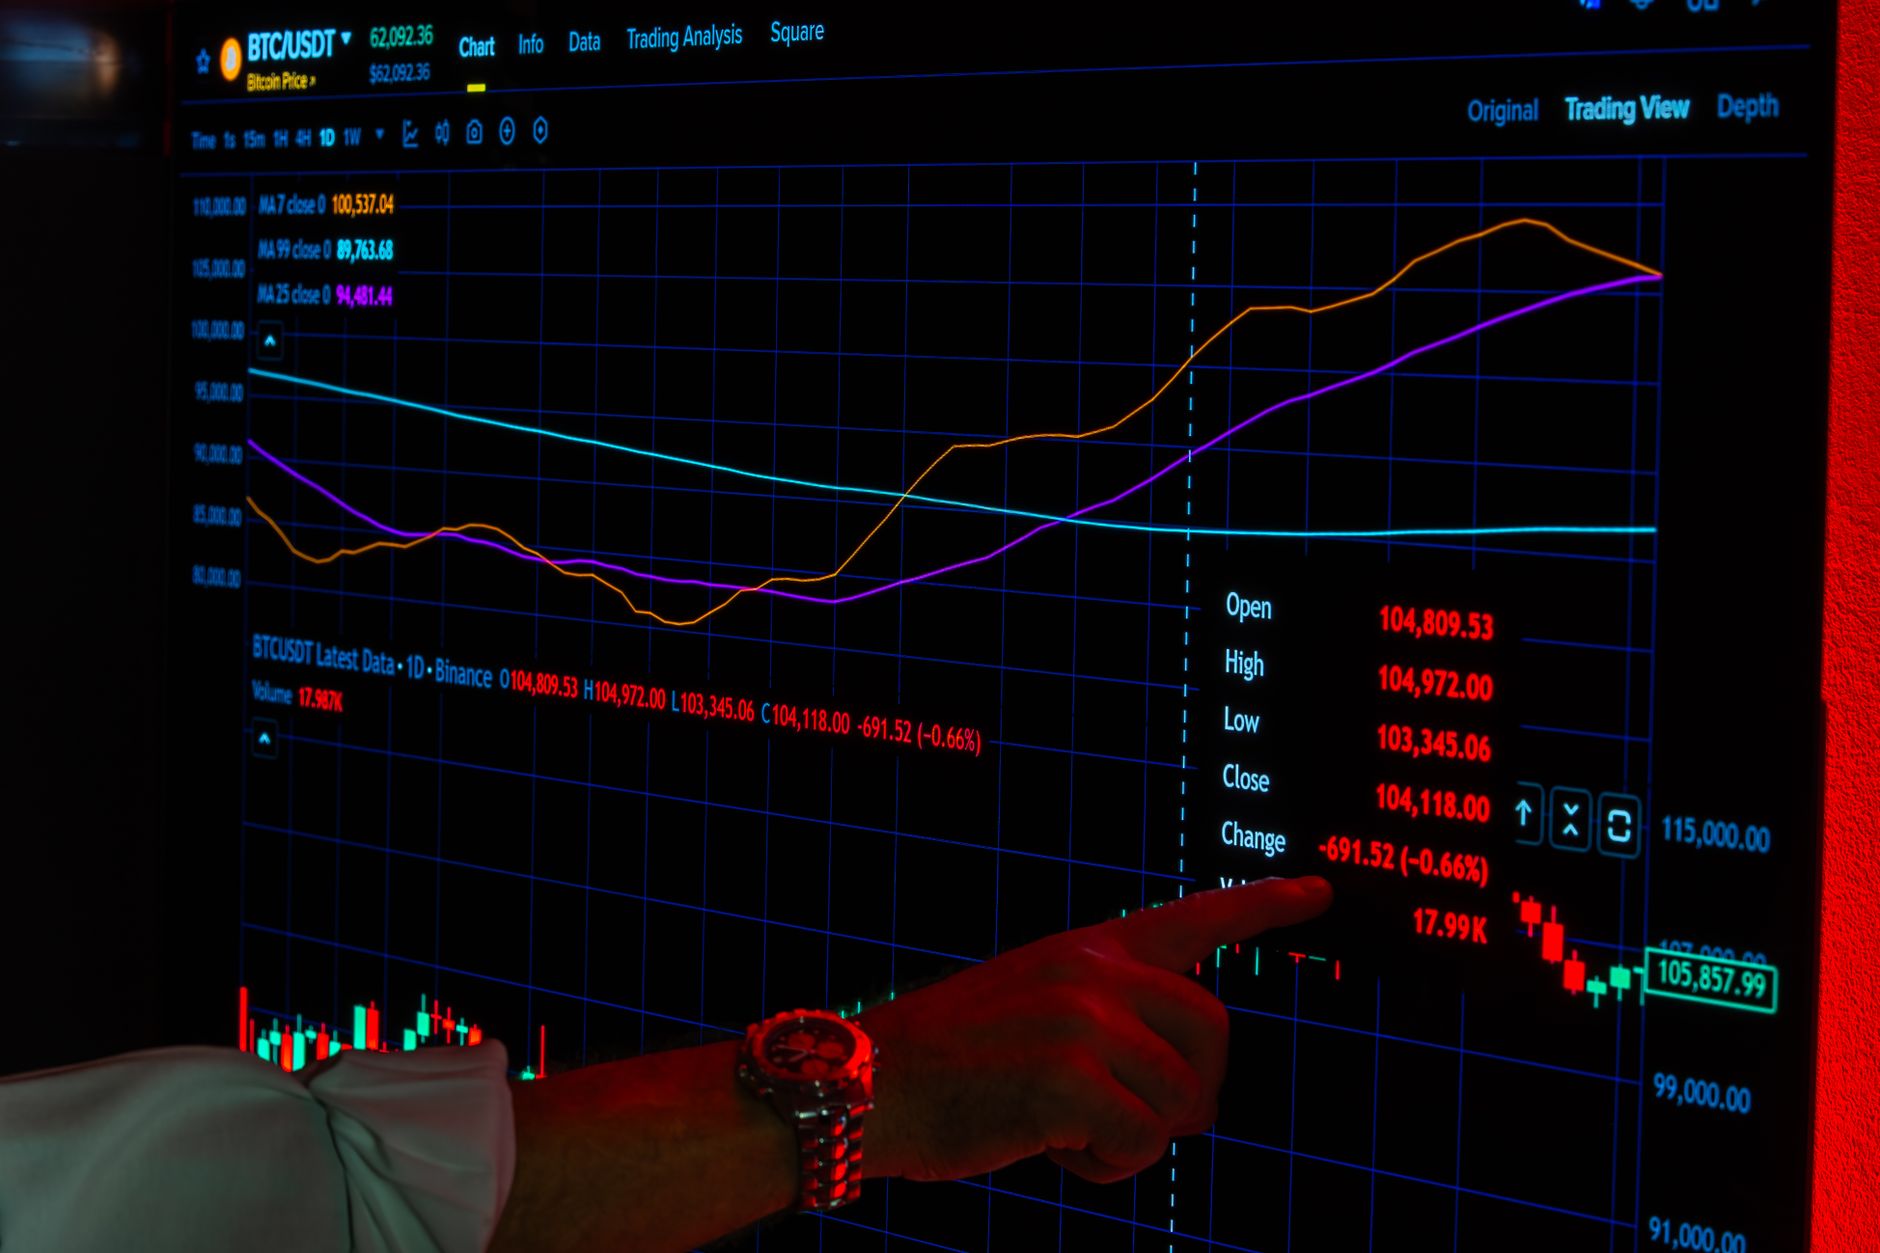
Bernstein’s expectation of swift SEC and CFTC rulemaking now becomes its own market signal. If agency-level rules arrive quickly and draw hard lines around stablecoin yields, platforms offering those products face a binary choice: restructure the product or face enforcement. The firms most exposed are those that built stablecoin reward programs into their core user acquisition strategy – where the yield isn’t incidental to the product but central to it.
Comments are closed, but trackbacks and pingbacks are open.